%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20548.6%2081.8'%20style='enable-background:new%200%200%20548.6%2081.8;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%23B3B2B2;}%20.st1{fill:%23333333;}%20.st2{fill:%23CB2A27;}%20.st3{fill:%239E2F2B;}%20.st4{fill:url(%23SVGID_1_);}%20.st5{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000081627807623978665650000007530117608280222350_);}%20.st6{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000124158375052983877420000016440253345571772322_);}%20.st7{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000162331698164625215240000016248320423653895854_);}%20.st8{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000176745200934897492200000012315166769339453352_);}%20%3c/style%3e%3cg%3e%3cg%3e%3cg%3e%3cpolygon%20class='st0'%20points='270.3,9.2%20268.5,9.2%20268.5,8.5%20272.9,8.5%20272.9,9.2%20271.1,9.2%20271.1,14%20270.3,14%20'/%3e%3cpolygon%20class='st0'%20points='273.5,8.5%20274.5,8.5%20276.3,13.1%20278.2,8.5%20279.1,8.5%20279.1,14%20278.5,14%20278.5,9.5%20278.5,9.5%20276.6,14%20276,14%20274.2,9.5%20274.2,9.5%20274.2,14%20273.5,14%20'/%3e%3c/g%3e%3c/g%3e%3cpath%20class='st0'%20d='M299.9,0h4.1v79.5h-4.1V0z'/%3e%3cg%3e%3cpath%20class='st1'%20d='M331.7,8.9h19.8c18.7,0,31.5,12.8,31.5,29.4v0.2c0,16.8-12.8,29.7-31.5,29.7h-19.8V8.9L331.7,8.9z%20M336.1,12.8V64h15.4c16.5,0,27-11.3,27-25.4v-0.2c0-14-10.4-25.7-27-25.7H336.1z'/%3e%3cpath%20class='st1'%20d='M390.3,8h5.1v5.7h-5.1V8z%20M390.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M405.4,75.3l2.4-3.3c5.1,3.9,11.2,6,17.5,6c10,0,16.9-5.7,16.9-16.8v-6.3c-3.8,5.3-9.5,10-18.1,10%20c-10.4,0-20.8-8-20.8-20.4v-0.2c0-12.5,10.4-20.5,20.8-20.5c8.6,0,14.5,4.5,18.1,9.7v-8.6h4.2v36.5c0,6.3-2,11.2-5.4,14.6%20c-3.8,3.8-9.4,5.7-15.7,5.7C418.1,82,411.4,79.7,405.4,75.3z%20M442.5,44.5v-0.2c0-10-8.9-16.5-17.8-16.5c-9.1,0-16.8,6.3-16.8,16.3%20v0.1c0,9.8,7.8,16.5,16.8,16.5C433.6,61,442.5,54.3,442.5,44.5z'/%3e%3cpath%20class='st1'%20d='M455.5,8h5.1v5.7h-5.1V8z%20M455.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M473.8,57V28.7h-6.3v-3.8h6.3V11h4.2v13.9h15.2v3.8H478v27.9c0,6.2,3.6,8.5,8.6,8.5c2.1,0,3.9-0.5,6.3-1.5%20v3.9c-2.3,1.1-4.4,1.5-7.1,1.5C479.2,69,473.8,65.4,473.8,57z'/%3e%3cpath%20class='st1'%20d='M496.7,55.5v-0.2c0-9.1,7.7-14,18.9-14c6,0,10.1,0.8,14.3,1.8v-1.8c0-8.8-5.3-13.3-14.2-13.3%20c-5.3,0-9.5,1.5-13.6,3.5l-1.5-3.6c4.7-2.3,9.4-3.8,15.4-3.8c5.9,0,10.6,1.7,13.6,4.7c2.9,2.9,4.4,6.8,4.4,12.2v27h-4.1v-7.2%20c-3,4.2-8.3,8.1-16.5,8.1C505.3,69.1,496.7,64.6,496.7,55.5z%20M530,51.9v-5c-3.6-0.9-8.5-2-14.6-2c-9.2,0-14.2,4.1-14.2,10.1v0.2%20c0,6.3,5.9,10,12.5,10C522.5,65.4,530,59.9,530,51.9z'/%3e%3cpath%20class='st1'%20d='M544.4,6.3h4.2v61.9h-4.2V6.3z'/%3e%3c/g%3e%3c/g%3e%3cpolygon%20points='20.5,8.6%2020.5,50.5%2048.1,50.5%2048.1,68.2%200,68.2%200,8.6%20'/%3e%3cpolygon%20points='76.7,8.6%2089,28.8%20101.3,8.6%20122.4,8.6%20122.4,68.2%20102,68.2%20102,40.4%2089.2,60%2088.4,60%2075.7,40.4%2075.7,68.2%2055.5,68.2%2055.5,8.6%20'/%3e%3cpath%20d='M163.5,33.1l-4.6,12.3h9.3L163.5,33.1z%20M153.6,8.2h20.1l25.1,60l-22.3,0l-3.1-7.9h-19.8l-3,7.9h-22L153.6,8.2z'/%3e%3cpolygon%20points='242.6,8.6%20235.1,19.8%20246.8,37.1%20266.1,8.6%20'/%3e%3cpolygon%20points='266.6,68.1%20246.7,38.7%20235.1,55.9%20243.4,68.1%20'/%3e%3cg%3e%3cpolygon%20class='st2'%20points='201.6,67.7%20221.9,37.8%20202.5,9.1%20224.7,9.1%20244.2,37.8%20223.9,67.7%20'/%3e%3cpath%20class='st3'%20d='M224.5,9.6l19.1,28.2l-19.9,29.4h-21l19.5-28.8l0.4-0.6l-0.4-0.6L203.4,9.6L224.5,9.6%20M225,8.6h-23.5%20l19.7,29.2l-20.6,30.4h23.5l20.6-30.4L225,8.6L225,8.6z'/%3e%3c/g%3e%3cg%3e%3clinearGradient%20id='SVGID_1_'%20gradientUnits='userSpaceOnUse'%20x1='220.9093'%20y1='-950.0897'%20x2='220.9093'%20y2='-925.641'%20gradientTransform='matrix(1%200%200%20-1%200%20-916)'%3e%3cstop%20offset='0'%20style='stop-color:%23FFFFFF'/%3e%3cstop%20offset='0.9448'%20style='stop-color:%23D83A16'/%3e%3c/linearGradient%3e%3cpath%20class='st4'%20d='M203.5,9.6h21l13.9,20.5c0,0-5.1,2.5-18.3,4L203.5,9.6z'/%3e%3c/g%3e%3clinearGradient%20id='SVGID_00000102544490061922048680000006716673136051575428_'%20gradientUnits='userSpaceOnUse'%20x1='-829.9603'%20y1='-469.8219'%20x2='-829.2181'%20y2='-469.8219'%20gradientTransform='matrix(0%2056.2842%20-56.2842%200%20-26433.2578%2046715.5)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000102544490061922048680000006716673136051575428_);'%20d='%20M1,43.5C6.8,41.1,13.7,39,19.6,38V9.6H1V43.5z'/%3e%3clinearGradient%20id='SVGID_00000103957968551173334310000005412737639992854954_'%20gradientUnits='userSpaceOnUse'%20x1='-824.1308'%20y1='-473.5818'%20x2='-823.3696'%20y2='-473.5818'%20gradientTransform='matrix(0%2040.0685%20-40.0685%200%20-18886.7422%2033025.9883)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000103957968551173334310000005412737639992854954_);'%20d='%20M89,30.6l-12.8-21H56.5v25.1c24.2-3,48.1-1.9,64.9,0.1V9.6H102L89,30.6z'/%3e%3clinearGradient%20id='SVGID_00000045609548158379760350000004638969150694955421_'%20gradientUnits='userSpaceOnUse'%20x1='-828.1707'%20y1='-470.2902'%20x2='-827.4019'%20y2='-470.2902'%20gradientTransform='matrix(0%2050.0393%20-50.0393%200%20-23369.248%2041443.8047)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000045609548158379760350000004638969150694955421_);'%20d='%20M154.3,9.2l-11.9,28.4c5.1,0.9,10.5,1.1,17.7,1.8l3.4-9.1l3.5,9.2c6.3,0.2,11.4-0.5,18.1-1.5L173,9.2L154.3,9.2L154.3,9.2L154.3,9.2%20z'/%3e%3clinearGradient%20id='SVGID_00000098218655395796564910000006749387513598408615_'%20gradientUnits='userSpaceOnUse'%20x1='-817.4011'%20y1='-476.8813'%20x2='-816.6498'%20y2='-476.8813'%20gradientTransform='matrix(0%2030.094%20-30.094%200%20-14101.042%2024605.1211)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000098218655395796564910000006749387513598408615_);'%20d='%20M243.1,9.6l-6.9,10.2l5.7,8.5c5.8-1.8,9.2-3.2,13.7-6l8.5-12.6H243.1L243.1,9.6z'/%3e%3c/svg%3e)
%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20548.6%2081.8'%20style='enable-background:new%200%200%20548.6%2081.8;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%23B3B2B2;}%20.st1{fill:%23FFFFFF;}%20.st2{fill:%23EDEDED;}%20.st3{fill:%23B2B2B2;}%20.st4{fill:%23CB2A27;}%20.st5{fill:%239E2F2B;}%20.st6{fill:url(%23SVGID_1_);}%20%3c/style%3e%3cg%3e%3cg%3e%3cg%3e%3cpolygon%20class='st0'%20points='270.3,9.2%20268.5,9.2%20268.5,8.5%20272.9,8.5%20272.9,9.2%20271.1,9.2%20271.1,14%20270.3,14%20'/%3e%3cpolygon%20class='st0'%20points='273.5,8.5%20274.5,8.5%20276.3,13.1%20278.2,8.5%20279.1,8.5%20279.1,14%20278.5,14%20278.5,9.5%20278.5,9.5%20276.6,14%20276,14%20274.2,9.5%20274.2,9.5%20274.2,14%20273.5,14%20'/%3e%3c/g%3e%3c/g%3e%3cpath%20class='st0'%20d='M299.9,0h4.1v79.5h-4.1V0z'/%3e%3cg%3e%3cpath%20class='st1'%20d='M331.7,8.9h19.8c18.7,0,31.5,12.8,31.5,29.4v0.2c0,16.8-12.8,29.7-31.5,29.7h-19.8V8.9L331.7,8.9z%20M336.1,12.8V64h15.4c16.5,0,27-11.3,27-25.4v-0.2c0-14-10.4-25.7-27-25.7H336.1z'/%3e%3cpath%20class='st1'%20d='M390.3,8h5.1v5.7h-5.1V8z%20M390.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M405.4,75.3l2.4-3.3c5.1,3.9,11.2,6,17.5,6c10,0,16.9-5.7,16.9-16.8v-6.3c-3.8,5.3-9.5,10-18.1,10%20c-10.4,0-20.8-8-20.8-20.4v-0.2c0-12.5,10.4-20.5,20.8-20.5c8.6,0,14.5,4.5,18.1,9.7v-8.6h4.2v36.5c0,6.3-2,11.2-5.4,14.6%20c-3.8,3.8-9.4,5.7-15.7,5.7C418.1,82,411.4,79.7,405.4,75.3z%20M442.5,44.5v-0.2c0-10-8.9-16.5-17.8-16.5c-9.1,0-16.8,6.3-16.8,16.3%20v0.1c0,9.8,7.8,16.5,16.8,16.5C433.6,61,442.5,54.3,442.5,44.5z'/%3e%3cpath%20class='st1'%20d='M455.5,8h5.1v5.7h-5.1V8z%20M455.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M473.8,57V28.7h-6.3v-3.8h6.3V11h4.2v13.9h15.2v3.8H478v27.9c0,6.2,3.6,8.5,8.6,8.5c2.1,0,3.9-0.5,6.3-1.5%20v3.9c-2.3,1.1-4.4,1.5-7.1,1.5C479.2,69,473.8,65.4,473.8,57z'/%3e%3cpath%20class='st1'%20d='M496.7,55.5v-0.2c0-9.1,7.7-14,18.9-14c6,0,10.1,0.8,14.3,1.8v-1.8c0-8.8-5.3-13.3-14.2-13.3%20c-5.3,0-9.5,1.5-13.6,3.5l-1.5-3.6c4.7-2.3,9.4-3.8,15.4-3.8c5.9,0,10.6,1.7,13.6,4.7c2.9,2.9,4.4,6.8,4.4,12.2v27h-4.1v-7.2%20c-3,4.2-8.3,8.1-16.5,8.1C505.3,69.1,496.7,64.6,496.7,55.5z%20M530,51.9v-5c-3.6-0.9-8.5-2-14.6-2c-9.2,0-14.2,4.1-14.2,10.1v0.2%20c0,6.3,5.9,10,12.5,10C522.5,65.4,530,59.9,530,51.9z'/%3e%3cpath%20class='st1'%20d='M544.4,6.3h4.2v61.9h-4.2V6.3z'/%3e%3c/g%3e%3cg%3e%3cg%3e%3cpolygon%20class='st2'%20points='0.5,67.9%200.5,9.1%2020.1,9.1%2020.1,51%2047.8,51%2047.8,67.9%20'/%3e%3cpath%20class='st3'%20d='M19.6,9.5v41.1v0.9h0.9h26.7v15.8H0.9V9.5H19.6%20M20.7,8.5H0v59.9h48.3V50.6H20.7V8.5L20.7,8.5z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='102.8,67.9%20102.8,38.8%2089.3,59.6%2088.9,59.6%2075.5,38.8%2075.5,67.9%2056.1,67.9%2056.1,9.1%2076.7,9.1%2089.3,29.6%20101.9,9.1%20122.4,9.1%20122.4,67.9%20'/%3e%3cpath%20class='st3'%20d='M121.9,9.5v58h-18.7v-27v-3.2l-1.8,2.7L89.2,59L76.8,39.8L75,37.1v3.2v27H56.6V9.5h19.8l12.1,19.8l0.8,1.4%20l0.8-1.4L102,9.5L121.9,9.5%20M122.9,8.5h-21.3L89.3,28.7L77,8.5H55.7v59.9h20.2V40.4l12.7,19.8h0.9l12.7-19.8v27.9h20.5V8.5H122.9%20z'/%3e%3c/g%3e%3cg%3e%3cpath%20class='st2'%20d='M177.5,67.9l-3.2-7.8h-20.5l-3,7.8h-21l24.8-59.3H174l24.8,59.3H177.5z%20M158.8,46h10.7l-5.3-14.2L158.8,46z'%20/%3e%3cpath%20class='st3'%20d='M173.7,9.1L198,67.5h-20.2l-2.9-7.2l-0.3-0.6H174h-19.9h-0.6l-0.3,0.6l-2.7,7.2h-20.1l24.4-58.4H173.7%20M158,46.5h1.4h9.4h1.4l-0.5-1.4L165,32.8l-0.9-2.4l-0.9,2.4l-4.7,12.4L158,46.5%20M174.3,8.1h-20.2l-25.2,60.2h22.2l3-7.8H174%20l3.2,7.8h22.3L174.3,8.1L174.3,8.1z%20M159.5,45.6l4.7-12.4l4.7,12.4H159.5L159.5,45.6z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='236.5,19.8%20243.7,9.1%20266.2,9.1%20247.7,36.2%20'/%3e%3cpath%20class='st3'%20d='M265.3,9.5l-17.7,26l-10.6-15.7L244,9.5L265.3,9.5%20M267.1,8.5h-23.5L236,19.6L247.8,37L267.1,8.5L267.1,8.5z%20'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='244.6,67.8%20236.7,56%20247.7,39.5%20266.8,67.8%20'/%3e%3cpath%20class='st3'%20d='M247.7,40.4l18.3,26.9h-21L237.3,56L247.7,40.4%20M247.7,38.8L236,56l8.3,12.4h23.2L247.7,38.8L247.7,38.8z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st4'%20points='202.4,67.9%20222.8,37.9%20203.3,9.1%20225.6,9.1%20245.1,37.9%20224.7,67.9%20'/%3e%3cpath%20class='st5'%20d='M225.3,9.5l19.2,28.2l-20.1,29.6h-21.1l19.6-29l0.5-0.6l-0.5-0.6L204.2,9.4h21.1%20M225.9,8.5h-23.5l19.9,29.3%20l-20.7,30.5H225l20.7-30.5L225.9,8.5L225.9,8.5z'/%3e%3c/g%3e%3cg%3e%3clinearGradient%20id='SVGID_1_'%20gradientUnits='userSpaceOnUse'%20x1='166.4754'%20y1='-918.2897'%20x2='166.4754'%20y2='-934.5494'%20gradientTransform='matrix(1.5092%200%200%201.5092%20-29.5361%201419.9884)'%3e%3cstop%20offset='0'%20style='stop-color:%23FFFFFF'/%3e%3cstop%20offset='0.9448'%20style='stop-color:%23D83A16'/%3e%3c/linearGradient%3e%3cpath%20class='st6'%20d='M204.2,9.5h21.1L239.2,30c0,0-5.1,2.4-18.4,3.9L204.2,9.5z'/%3e%3c/g%3e%3cpath%20class='st1'%20d='M0.9,43.6c5.9-2.4,12.7-4.5,18.7-5.6V9.5H0.9V43.6z'/%3e%3cpath%20class='st1'%20d='M89.3,30.6L76.5,9.5H56.7v25.2c24.3-3,48.3-2,65.2,0.2V9.5h-19.6L89.3,30.6z'/%3e%3cpath%20class='st1'%20d='M154.8,9.1l-11.9,28.5c5.1,0.9,10.6,1.1,17.8,1.8l3.5-9.2l3.5,9.2c6.3,0.2,11.5-0.5,18.3-1.5L173.7,9.1H154.8%20z'/%3e%3cpath%20class='st1'%20d='M244,9.5l-6.9,10.3l5.7,8.5c5.9-1.8,9.2-3.2,13.7-6l8.6-12.7H244z'/%3e%3c/g%3e%3c/g%3e%3c/svg%3e)


On Tokenized Stock Rights
Quick Take
Robinhood refuses to delist AMC's stock token
On September 3, AMC CEO Adam Aron publicly called out Robinhood for listing an unregistered token tied to AMC stock without the company's consent. Aron doubled down the next day, demanding Robinhood cease and desist, describing the offshore Jersey issuance as a "quasi-fake market," and threatening to alert the SEC. Robinhood’s chief legal officer, Dan Gallagher, rejected the demand that same day, and the token remains active.
Appearing on CNBC on September 9, Tenev delivered Robinhood’s first televised response, arguing that while companies control their own stock, they don't hold veto power over third parties offering financial products referenced to those shares. He laid out his case in detail in a September 11 post, distinguishing between tokenized securities that represent or issue the underlying stock and independent securities whose value merely references it. In the latter case, Tenev argued, the underlying company should not have veto power over the third party's product, pointing to unsponsored ADRs and traditional structured products as established market precedents.
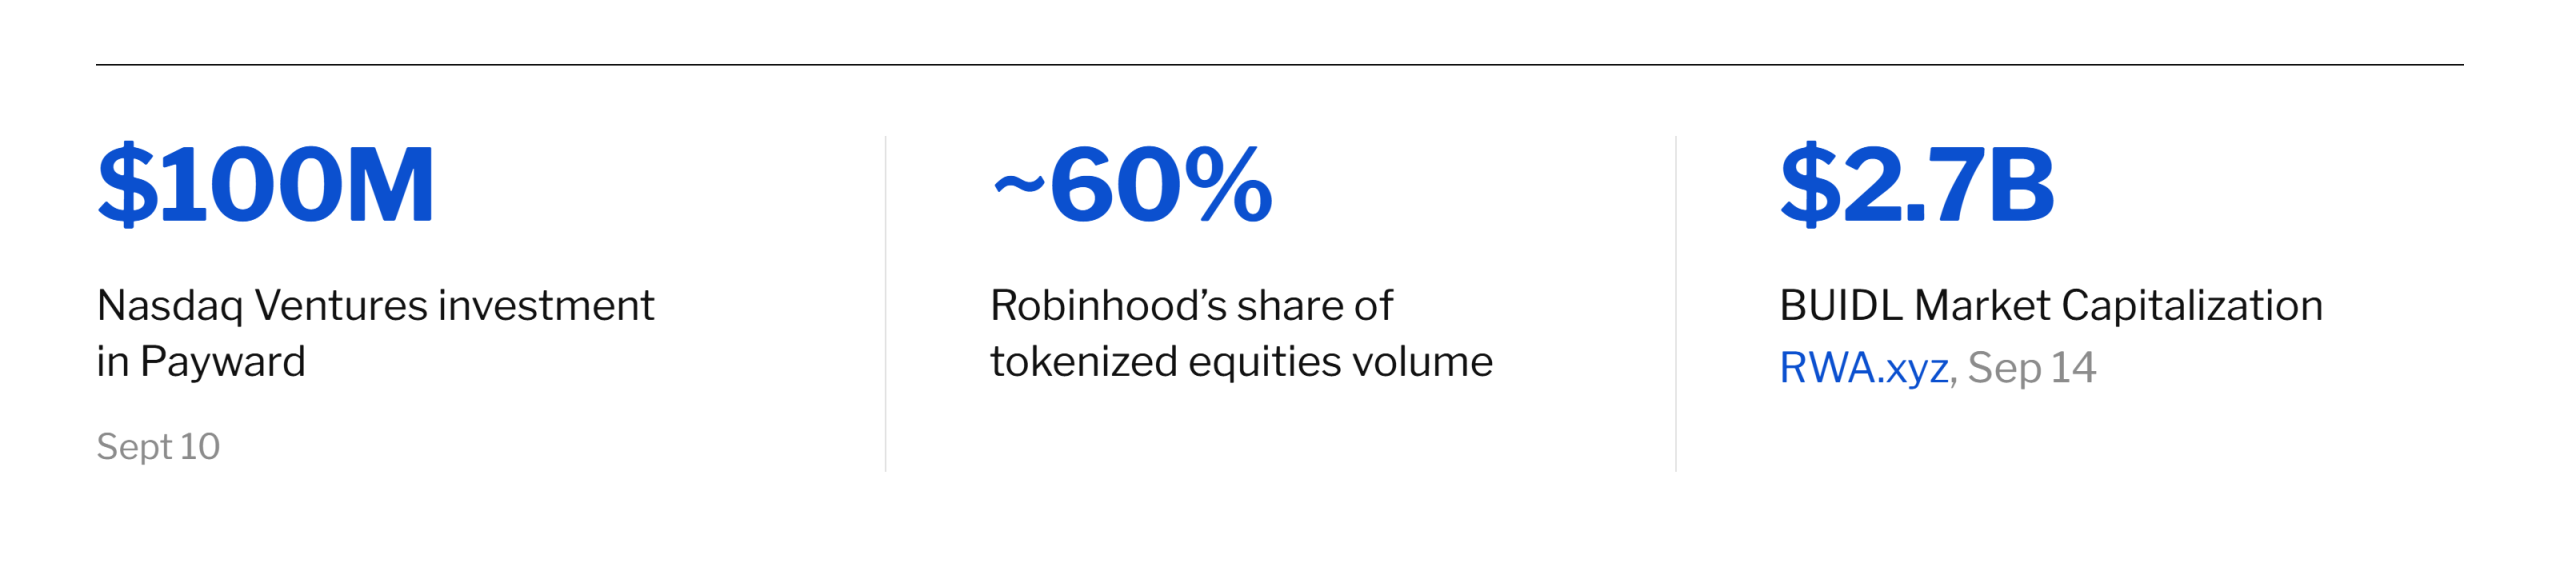
That same week, Nasdaq backed a different structure. On September 10, Nasdaq Ventures invested $100 million in Payward at a $21 billion valuation, expanding a partnership struck in March. The two are building Nasdaq Equity Tokens for a Q2 2027 launch via Kraken, with Payward adopting Nasdaq surveillance tech. Unlike Robinhood's synthetic debt notes, these tokens act as direct stock representations carrying full voting rights, requiring explicit corporate consent and regulatory approval.
Nasdaq Equity Tokens would join a segment that accounts for 12.7% of tokenized equities today. Tokens issued without the underlying company's consent stood at $2.43 billion on September 13, or 84.5% of tokenized equity market capitalization. Consented issuance was $365 million and has barely moved in a year, sitting near $300 million last September while the rest of the market grew from roughly $540 million to $2.9 billion. Consented shares were the majority of tokenized equities until September 18, 2025. Everything added since has been issued without consent.
Debate surrounding rights of tokenized equities holders will continue to heat up as the space develops. It is currently unclear if tokenized equities holders even care about whether they can vote with their tokenized shares vs. holding these tokenized shares purely for price exposure. With that being said, the Robinhood team is not ignoring the potential demand for utility, with Robinhood Crypto’s lead describing plans to offer “redemptions for shares 1:1 with voting for eligible Stock Token holders.“
Robinhood Stock Tokens now carry most tokenized equity volume
Robinhood Stock Tokens accounted for roughly 60% of tokenized equity transfer volume in early September, against $170 million of the segment's $2.9 billion in market capitalization, so a sixteenth of the float is producing more than half the trading. Much of that trading has been gas-subsidized since Robinhood Chain launched. Robinhood Chain’s gas subsidy ends on September 29.
Binance follows a similar timeline with bStocks, which dominated on-chain equity volume for most of the summer. Maker fees were waived through August 31, and withdrawal fees to BNB Chain wallets remain covered through late September.
Together, these two platforms drive the vast majority of the sector's activity, and both are pulling back their subsidies within weeks. October will be the true test of how much volume is genuinely organic.
BUIDL loses half its market share
BUIDL sits at roughly $2.70 billion, below its March 2025 levels, even as the broader tokenized Treasury market expanded from $4 billion to $15.9 billion. Over that same period, BUIDL's market share fell from a peak near 46 percent to roughly 18 percent.
That drop in market share was not caused by a lack of collateral adoption. Prime brokers, major exchanges including Deribit, Crypto.com, Binance, and OKX, and even a CFTC pilot for futures commission merchants all accepted BUIDL as margin during that period. The real friction comes from the onboarding process, where a $5 million minimum investment and complex process through Securitize limits buyer access. That friction allowed Circle to overtake BlackRock at the top of the market in March, while traditional asset managers captured most of the new supply.
The August 31 agreement between ICE and tZERO targets this exact problem. Clearinghouse acceptance reaches traditional firms that do not trade crypto and hold far larger margin balances. That brings in a fresh buyer base rather than just another venue for existing traders.
Subscribe to Tokenization Briefing
Tokenization Briefing
Get 2 days early access to each issue by joining the mailing list.
© 2026 The Block Crypto, Inc. All Rights Reserved. Newsletters are provided for informational purposes only. It is not offered or intended to be used as legal, tax, investment, financial, or other advice.