%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20548.6%2081.8'%20style='enable-background:new%200%200%20548.6%2081.8;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%23B3B2B2;}%20.st1{fill:%23333333;}%20.st2{fill:%23CB2A27;}%20.st3{fill:%239E2F2B;}%20.st4{fill:url(%23SVGID_1_);}%20.st5{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000081627807623978665650000007530117608280222350_);}%20.st6{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000124158375052983877420000016440253345571772322_);}%20.st7{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000162331698164625215240000016248320423653895854_);}%20.st8{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000176745200934897492200000012315166769339453352_);}%20%3c/style%3e%3cg%3e%3cg%3e%3cg%3e%3cpolygon%20class='st0'%20points='270.3,9.2%20268.5,9.2%20268.5,8.5%20272.9,8.5%20272.9,9.2%20271.1,9.2%20271.1,14%20270.3,14%20'/%3e%3cpolygon%20class='st0'%20points='273.5,8.5%20274.5,8.5%20276.3,13.1%20278.2,8.5%20279.1,8.5%20279.1,14%20278.5,14%20278.5,9.5%20278.5,9.5%20276.6,14%20276,14%20274.2,9.5%20274.2,9.5%20274.2,14%20273.5,14%20'/%3e%3c/g%3e%3c/g%3e%3cpath%20class='st0'%20d='M299.9,0h4.1v79.5h-4.1V0z'/%3e%3cg%3e%3cpath%20class='st1'%20d='M331.7,8.9h19.8c18.7,0,31.5,12.8,31.5,29.4v0.2c0,16.8-12.8,29.7-31.5,29.7h-19.8V8.9L331.7,8.9z%20M336.1,12.8V64h15.4c16.5,0,27-11.3,27-25.4v-0.2c0-14-10.4-25.7-27-25.7H336.1z'/%3e%3cpath%20class='st1'%20d='M390.3,8h5.1v5.7h-5.1V8z%20M390.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M405.4,75.3l2.4-3.3c5.1,3.9,11.2,6,17.5,6c10,0,16.9-5.7,16.9-16.8v-6.3c-3.8,5.3-9.5,10-18.1,10%20c-10.4,0-20.8-8-20.8-20.4v-0.2c0-12.5,10.4-20.5,20.8-20.5c8.6,0,14.5,4.5,18.1,9.7v-8.6h4.2v36.5c0,6.3-2,11.2-5.4,14.6%20c-3.8,3.8-9.4,5.7-15.7,5.7C418.1,82,411.4,79.7,405.4,75.3z%20M442.5,44.5v-0.2c0-10-8.9-16.5-17.8-16.5c-9.1,0-16.8,6.3-16.8,16.3%20v0.1c0,9.8,7.8,16.5,16.8,16.5C433.6,61,442.5,54.3,442.5,44.5z'/%3e%3cpath%20class='st1'%20d='M455.5,8h5.1v5.7h-5.1V8z%20M455.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M473.8,57V28.7h-6.3v-3.8h6.3V11h4.2v13.9h15.2v3.8H478v27.9c0,6.2,3.6,8.5,8.6,8.5c2.1,0,3.9-0.5,6.3-1.5%20v3.9c-2.3,1.1-4.4,1.5-7.1,1.5C479.2,69,473.8,65.4,473.8,57z'/%3e%3cpath%20class='st1'%20d='M496.7,55.5v-0.2c0-9.1,7.7-14,18.9-14c6,0,10.1,0.8,14.3,1.8v-1.8c0-8.8-5.3-13.3-14.2-13.3%20c-5.3,0-9.5,1.5-13.6,3.5l-1.5-3.6c4.7-2.3,9.4-3.8,15.4-3.8c5.9,0,10.6,1.7,13.6,4.7c2.9,2.9,4.4,6.8,4.4,12.2v27h-4.1v-7.2%20c-3,4.2-8.3,8.1-16.5,8.1C505.3,69.1,496.7,64.6,496.7,55.5z%20M530,51.9v-5c-3.6-0.9-8.5-2-14.6-2c-9.2,0-14.2,4.1-14.2,10.1v0.2%20c0,6.3,5.9,10,12.5,10C522.5,65.4,530,59.9,530,51.9z'/%3e%3cpath%20class='st1'%20d='M544.4,6.3h4.2v61.9h-4.2V6.3z'/%3e%3c/g%3e%3c/g%3e%3cpolygon%20points='20.5,8.6%2020.5,50.5%2048.1,50.5%2048.1,68.2%200,68.2%200,8.6%20'/%3e%3cpolygon%20points='76.7,8.6%2089,28.8%20101.3,8.6%20122.4,8.6%20122.4,68.2%20102,68.2%20102,40.4%2089.2,60%2088.4,60%2075.7,40.4%2075.7,68.2%2055.5,68.2%2055.5,8.6%20'/%3e%3cpath%20d='M163.5,33.1l-4.6,12.3h9.3L163.5,33.1z%20M153.6,8.2h20.1l25.1,60l-22.3,0l-3.1-7.9h-19.8l-3,7.9h-22L153.6,8.2z'/%3e%3cpolygon%20points='242.6,8.6%20235.1,19.8%20246.8,37.1%20266.1,8.6%20'/%3e%3cpolygon%20points='266.6,68.1%20246.7,38.7%20235.1,55.9%20243.4,68.1%20'/%3e%3cg%3e%3cpolygon%20class='st2'%20points='201.6,67.7%20221.9,37.8%20202.5,9.1%20224.7,9.1%20244.2,37.8%20223.9,67.7%20'/%3e%3cpath%20class='st3'%20d='M224.5,9.6l19.1,28.2l-19.9,29.4h-21l19.5-28.8l0.4-0.6l-0.4-0.6L203.4,9.6L224.5,9.6%20M225,8.6h-23.5%20l19.7,29.2l-20.6,30.4h23.5l20.6-30.4L225,8.6L225,8.6z'/%3e%3c/g%3e%3cg%3e%3clinearGradient%20id='SVGID_1_'%20gradientUnits='userSpaceOnUse'%20x1='220.9093'%20y1='-950.0897'%20x2='220.9093'%20y2='-925.641'%20gradientTransform='matrix(1%200%200%20-1%200%20-916)'%3e%3cstop%20offset='0'%20style='stop-color:%23FFFFFF'/%3e%3cstop%20offset='0.9448'%20style='stop-color:%23D83A16'/%3e%3c/linearGradient%3e%3cpath%20class='st4'%20d='M203.5,9.6h21l13.9,20.5c0,0-5.1,2.5-18.3,4L203.5,9.6z'/%3e%3c/g%3e%3clinearGradient%20id='SVGID_00000102544490061922048680000006716673136051575428_'%20gradientUnits='userSpaceOnUse'%20x1='-829.9603'%20y1='-469.8219'%20x2='-829.2181'%20y2='-469.8219'%20gradientTransform='matrix(0%2056.2842%20-56.2842%200%20-26433.2578%2046715.5)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000102544490061922048680000006716673136051575428_);'%20d='%20M1,43.5C6.8,41.1,13.7,39,19.6,38V9.6H1V43.5z'/%3e%3clinearGradient%20id='SVGID_00000103957968551173334310000005412737639992854954_'%20gradientUnits='userSpaceOnUse'%20x1='-824.1308'%20y1='-473.5818'%20x2='-823.3696'%20y2='-473.5818'%20gradientTransform='matrix(0%2040.0685%20-40.0685%200%20-18886.7422%2033025.9883)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000103957968551173334310000005412737639992854954_);'%20d='%20M89,30.6l-12.8-21H56.5v25.1c24.2-3,48.1-1.9,64.9,0.1V9.6H102L89,30.6z'/%3e%3clinearGradient%20id='SVGID_00000045609548158379760350000004638969150694955421_'%20gradientUnits='userSpaceOnUse'%20x1='-828.1707'%20y1='-470.2902'%20x2='-827.4019'%20y2='-470.2902'%20gradientTransform='matrix(0%2050.0393%20-50.0393%200%20-23369.248%2041443.8047)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000045609548158379760350000004638969150694955421_);'%20d='%20M154.3,9.2l-11.9,28.4c5.1,0.9,10.5,1.1,17.7,1.8l3.4-9.1l3.5,9.2c6.3,0.2,11.4-0.5,18.1-1.5L173,9.2L154.3,9.2L154.3,9.2L154.3,9.2%20z'/%3e%3clinearGradient%20id='SVGID_00000098218655395796564910000006749387513598408615_'%20gradientUnits='userSpaceOnUse'%20x1='-817.4011'%20y1='-476.8813'%20x2='-816.6498'%20y2='-476.8813'%20gradientTransform='matrix(0%2030.094%20-30.094%200%20-14101.042%2024605.1211)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000098218655395796564910000006749387513598408615_);'%20d='%20M243.1,9.6l-6.9,10.2l5.7,8.5c5.8-1.8,9.2-3.2,13.7-6l8.5-12.6H243.1L243.1,9.6z'/%3e%3c/svg%3e)
%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20548.6%2081.8'%20style='enable-background:new%200%200%20548.6%2081.8;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%23B3B2B2;}%20.st1{fill:%23FFFFFF;}%20.st2{fill:%23EDEDED;}%20.st3{fill:%23B2B2B2;}%20.st4{fill:%23CB2A27;}%20.st5{fill:%239E2F2B;}%20.st6{fill:url(%23SVGID_1_);}%20%3c/style%3e%3cg%3e%3cg%3e%3cg%3e%3cpolygon%20class='st0'%20points='270.3,9.2%20268.5,9.2%20268.5,8.5%20272.9,8.5%20272.9,9.2%20271.1,9.2%20271.1,14%20270.3,14%20'/%3e%3cpolygon%20class='st0'%20points='273.5,8.5%20274.5,8.5%20276.3,13.1%20278.2,8.5%20279.1,8.5%20279.1,14%20278.5,14%20278.5,9.5%20278.5,9.5%20276.6,14%20276,14%20274.2,9.5%20274.2,9.5%20274.2,14%20273.5,14%20'/%3e%3c/g%3e%3c/g%3e%3cpath%20class='st0'%20d='M299.9,0h4.1v79.5h-4.1V0z'/%3e%3cg%3e%3cpath%20class='st1'%20d='M331.7,8.9h19.8c18.7,0,31.5,12.8,31.5,29.4v0.2c0,16.8-12.8,29.7-31.5,29.7h-19.8V8.9L331.7,8.9z%20M336.1,12.8V64h15.4c16.5,0,27-11.3,27-25.4v-0.2c0-14-10.4-25.7-27-25.7H336.1z'/%3e%3cpath%20class='st1'%20d='M390.3,8h5.1v5.7h-5.1V8z%20M390.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M405.4,75.3l2.4-3.3c5.1,3.9,11.2,6,17.5,6c10,0,16.9-5.7,16.9-16.8v-6.3c-3.8,5.3-9.5,10-18.1,10%20c-10.4,0-20.8-8-20.8-20.4v-0.2c0-12.5,10.4-20.5,20.8-20.5c8.6,0,14.5,4.5,18.1,9.7v-8.6h4.2v36.5c0,6.3-2,11.2-5.4,14.6%20c-3.8,3.8-9.4,5.7-15.7,5.7C418.1,82,411.4,79.7,405.4,75.3z%20M442.5,44.5v-0.2c0-10-8.9-16.5-17.8-16.5c-9.1,0-16.8,6.3-16.8,16.3%20v0.1c0,9.8,7.8,16.5,16.8,16.5C433.6,61,442.5,54.3,442.5,44.5z'/%3e%3cpath%20class='st1'%20d='M455.5,8h5.1v5.7h-5.1V8z%20M455.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M473.8,57V28.7h-6.3v-3.8h6.3V11h4.2v13.9h15.2v3.8H478v27.9c0,6.2,3.6,8.5,8.6,8.5c2.1,0,3.9-0.5,6.3-1.5%20v3.9c-2.3,1.1-4.4,1.5-7.1,1.5C479.2,69,473.8,65.4,473.8,57z'/%3e%3cpath%20class='st1'%20d='M496.7,55.5v-0.2c0-9.1,7.7-14,18.9-14c6,0,10.1,0.8,14.3,1.8v-1.8c0-8.8-5.3-13.3-14.2-13.3%20c-5.3,0-9.5,1.5-13.6,3.5l-1.5-3.6c4.7-2.3,9.4-3.8,15.4-3.8c5.9,0,10.6,1.7,13.6,4.7c2.9,2.9,4.4,6.8,4.4,12.2v27h-4.1v-7.2%20c-3,4.2-8.3,8.1-16.5,8.1C505.3,69.1,496.7,64.6,496.7,55.5z%20M530,51.9v-5c-3.6-0.9-8.5-2-14.6-2c-9.2,0-14.2,4.1-14.2,10.1v0.2%20c0,6.3,5.9,10,12.5,10C522.5,65.4,530,59.9,530,51.9z'/%3e%3cpath%20class='st1'%20d='M544.4,6.3h4.2v61.9h-4.2V6.3z'/%3e%3c/g%3e%3cg%3e%3cg%3e%3cpolygon%20class='st2'%20points='0.5,67.9%200.5,9.1%2020.1,9.1%2020.1,51%2047.8,51%2047.8,67.9%20'/%3e%3cpath%20class='st3'%20d='M19.6,9.5v41.1v0.9h0.9h26.7v15.8H0.9V9.5H19.6%20M20.7,8.5H0v59.9h48.3V50.6H20.7V8.5L20.7,8.5z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='102.8,67.9%20102.8,38.8%2089.3,59.6%2088.9,59.6%2075.5,38.8%2075.5,67.9%2056.1,67.9%2056.1,9.1%2076.7,9.1%2089.3,29.6%20101.9,9.1%20122.4,9.1%20122.4,67.9%20'/%3e%3cpath%20class='st3'%20d='M121.9,9.5v58h-18.7v-27v-3.2l-1.8,2.7L89.2,59L76.8,39.8L75,37.1v3.2v27H56.6V9.5h19.8l12.1,19.8l0.8,1.4%20l0.8-1.4L102,9.5L121.9,9.5%20M122.9,8.5h-21.3L89.3,28.7L77,8.5H55.7v59.9h20.2V40.4l12.7,19.8h0.9l12.7-19.8v27.9h20.5V8.5H122.9%20z'/%3e%3c/g%3e%3cg%3e%3cpath%20class='st2'%20d='M177.5,67.9l-3.2-7.8h-20.5l-3,7.8h-21l24.8-59.3H174l24.8,59.3H177.5z%20M158.8,46h10.7l-5.3-14.2L158.8,46z'%20/%3e%3cpath%20class='st3'%20d='M173.7,9.1L198,67.5h-20.2l-2.9-7.2l-0.3-0.6H174h-19.9h-0.6l-0.3,0.6l-2.7,7.2h-20.1l24.4-58.4H173.7%20M158,46.5h1.4h9.4h1.4l-0.5-1.4L165,32.8l-0.9-2.4l-0.9,2.4l-4.7,12.4L158,46.5%20M174.3,8.1h-20.2l-25.2,60.2h22.2l3-7.8H174%20l3.2,7.8h22.3L174.3,8.1L174.3,8.1z%20M159.5,45.6l4.7-12.4l4.7,12.4H159.5L159.5,45.6z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='236.5,19.8%20243.7,9.1%20266.2,9.1%20247.7,36.2%20'/%3e%3cpath%20class='st3'%20d='M265.3,9.5l-17.7,26l-10.6-15.7L244,9.5L265.3,9.5%20M267.1,8.5h-23.5L236,19.6L247.8,37L267.1,8.5L267.1,8.5z%20'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='244.6,67.8%20236.7,56%20247.7,39.5%20266.8,67.8%20'/%3e%3cpath%20class='st3'%20d='M247.7,40.4l18.3,26.9h-21L237.3,56L247.7,40.4%20M247.7,38.8L236,56l8.3,12.4h23.2L247.7,38.8L247.7,38.8z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st4'%20points='202.4,67.9%20222.8,37.9%20203.3,9.1%20225.6,9.1%20245.1,37.9%20224.7,67.9%20'/%3e%3cpath%20class='st5'%20d='M225.3,9.5l19.2,28.2l-20.1,29.6h-21.1l19.6-29l0.5-0.6l-0.5-0.6L204.2,9.4h21.1%20M225.9,8.5h-23.5l19.9,29.3%20l-20.7,30.5H225l20.7-30.5L225.9,8.5L225.9,8.5z'/%3e%3c/g%3e%3cg%3e%3clinearGradient%20id='SVGID_1_'%20gradientUnits='userSpaceOnUse'%20x1='166.4754'%20y1='-918.2897'%20x2='166.4754'%20y2='-934.5494'%20gradientTransform='matrix(1.5092%200%200%201.5092%20-29.5361%201419.9884)'%3e%3cstop%20offset='0'%20style='stop-color:%23FFFFFF'/%3e%3cstop%20offset='0.9448'%20style='stop-color:%23D83A16'/%3e%3c/linearGradient%3e%3cpath%20class='st6'%20d='M204.2,9.5h21.1L239.2,30c0,0-5.1,2.4-18.4,3.9L204.2,9.5z'/%3e%3c/g%3e%3cpath%20class='st1'%20d='M0.9,43.6c5.9-2.4,12.7-4.5,18.7-5.6V9.5H0.9V43.6z'/%3e%3cpath%20class='st1'%20d='M89.3,30.6L76.5,9.5H56.7v25.2c24.3-3,48.3-2,65.2,0.2V9.5h-19.6L89.3,30.6z'/%3e%3cpath%20class='st1'%20d='M154.8,9.1l-11.9,28.5c5.1,0.9,10.6,1.1,17.8,1.8l3.5-9.2l3.5,9.2c6.3,0.2,11.5-0.5,18.3-1.5L173.7,9.1H154.8%20z'/%3e%3cpath%20class='st1'%20d='M244,9.5l-6.9,10.3l5.7,8.5c5.9-1.8,9.2-3.2,13.7-6l8.6-12.7H244z'/%3e%3c/g%3e%3c/g%3e%3c/svg%3e)


Stablecoin Holders Are Foregoing $12 Billion a Year in Yield. Here's Why.
Quick Take
The Fed Raises Rates
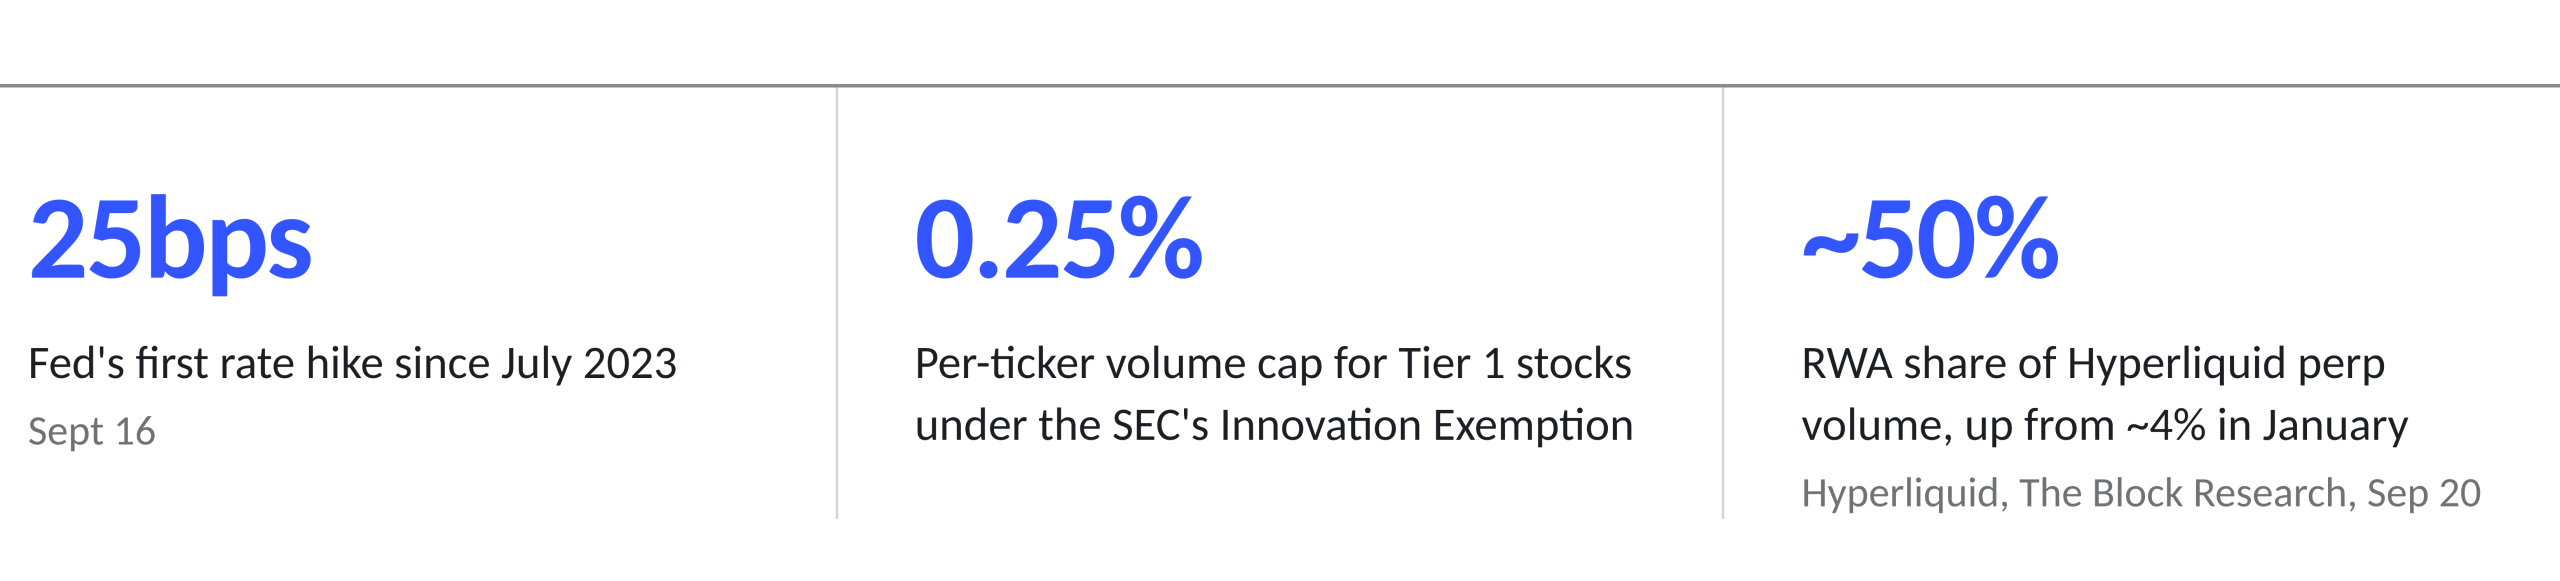
The Fed increased its benchmark rate by 25bp to reach a 3.75% - 4% target range on September 16, with 16 of 18 FOMC participants expecting at least one more rate hike this year. Hikes are expected to continue until the Fed reaches a target range of 4.5% - 4.75% in mid-2027, in an attempt to cool stubbornly high inflation.
At a roughly $310B stablecoin market cap and a 4% rate on treasuries, holders are on pace to collectively forgo $12B per year in stablecoin yield to issuers like Circle and Tether, with each 25bp increase adding another $775 million in opportunity cost.
This dynamic led to rapid growth in tokenized treasuries, with a series of rate hikes in 2022 and 2023 preceding a $14 billion increase in market cap, rising from under 0.5% to over 5% of the total stablecoin value.
This rising opportunity cost and growth of tokenized treasuries was compounded by the stablecoin yield ban introduced by the GENIUS Act on July 18, 2025. GENIUS made it illegal for issuers to pass yield back to stablecoin holders.
To circumvent the ban, stablecoin issuers started routing yield back to holders via affiliates, positioning the payouts as rewards instead of direct payouts from the issuer:
- Coinbase pays USDC holders 3.5% APY, positioned as loyalty rewards, arguing that non-issuers distributing rewards fall outside the ban.
- PayPal offers 3.7% on PYUSD, promoted as a loyalty reward.
- Kraken pays USDG holders via its "Global Dollar Rewards" program.
In response, the OCC and FDIC proposed rules that treat indirect payouts as violations of the ban. With the GENIUS Act scheduled to take effect in Jan 2027, this should drive increased demand for tokenized treasuries.
Although stablecoins retain many structural advantages over tokenized treasuries, including better composability and frictionless retail access, we’ll likely see stablecoin issuers increasingly enter the tokenized treasury market as a hedge.
The SEC’s Innovation Exemption
The SEC issued its Innovation Exemption on September 17, allowing for the trading of tokenized stocks in the U.S. Although the exemption limits the volume a Tokenized Securities Venue can facilitate to 0.25% of a stock's prior-month average daily volume, this sandbox is a positive signal that regulators are willing to provide a path for tokenized equities.
The market reacted well to the news, with shares of Robinhood and Coinbase, both of which offer tokenized stocks overseas, rising 5% and 6% on the day of the announcement. The order came just two days after the CLARITY Act failed in the Senate, showing the SEC is willing to move forward on tokenization using its own authority rather than waiting on Congress.
Although the direction is positive, the pilot is tightly constrained:
- Venues are restricted to 75 Tier 1 tickers
- Access must be permissioned
- Tokens need full shareholder rights
- Issuers can block tokenization of their stock
The volume cap is also small relative to existing demand. Onchain DEX volume in tokenized SPY already averages $59.1 million a day, or 77% of the $76.3 million a single venue would be allowed to trade. With the exemption set to expire in 2031, the next five years will need to show that these limits can increase safely.
RWA perps drove over half of Hyperliquid's volume
RWA perps crossed 50% of Hyperliquid's weekly perp volume for the first time in the week ending July 19, and peaked at 62.7% two weeks later, when they did $37.7 billion in a single week. Commodities such as oil, silver and gold pushed the share to 30 - 40% from February through May, before single stocks took over in June and July and reached roughly 70% of RWA volume.
The share has since fallen to 22%, but the drop reflects crypto recovering as much as RWAs fading. RWA volume cooled from its peak to about $13 - 14 billion a week, while crypto volume rebounded from $16 billion in mid-August to $47 - 61 billion in a week. In under a year, RWA perps have gone from zero to a steady $13 - 20 billion a week on Hyperliquid.
Subscribe to Tokenization Briefing
Tokenization Briefing
Get 2 days early access to each issue by joining the mailing list.
© 2026 The Block Crypto, Inc. All Rights Reserved. Newsletters are provided for informational purposes only. It is not offered or intended to be used as legal, tax, investment, financial, or other advice.
More from Tokenization Briefing