%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20548.6%2081.8'%20style='enable-background:new%200%200%20548.6%2081.8;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%23B3B2B2;}%20.st1{fill:%23333333;}%20.st2{fill:%23CB2A27;}%20.st3{fill:%239E2F2B;}%20.st4{fill:url(%23SVGID_1_);}%20.st5{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000081627807623978665650000007530117608280222350_);}%20.st6{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000124158375052983877420000016440253345571772322_);}%20.st7{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000162331698164625215240000016248320423653895854_);}%20.st8{fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000176745200934897492200000012315166769339453352_);}%20%3c/style%3e%3cg%3e%3cg%3e%3cg%3e%3cpolygon%20class='st0'%20points='270.3,9.2%20268.5,9.2%20268.5,8.5%20272.9,8.5%20272.9,9.2%20271.1,9.2%20271.1,14%20270.3,14%20'/%3e%3cpolygon%20class='st0'%20points='273.5,8.5%20274.5,8.5%20276.3,13.1%20278.2,8.5%20279.1,8.5%20279.1,14%20278.5,14%20278.5,9.5%20278.5,9.5%20276.6,14%20276,14%20274.2,9.5%20274.2,9.5%20274.2,14%20273.5,14%20'/%3e%3c/g%3e%3c/g%3e%3cpath%20class='st0'%20d='M299.9,0h4.1v79.5h-4.1V0z'/%3e%3cg%3e%3cpath%20class='st1'%20d='M331.7,8.9h19.8c18.7,0,31.5,12.8,31.5,29.4v0.2c0,16.8-12.8,29.7-31.5,29.7h-19.8V8.9L331.7,8.9z%20M336.1,12.8V64h15.4c16.5,0,27-11.3,27-25.4v-0.2c0-14-10.4-25.7-27-25.7H336.1z'/%3e%3cpath%20class='st1'%20d='M390.3,8h5.1v5.7h-5.1V8z%20M390.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M405.4,75.3l2.4-3.3c5.1,3.9,11.2,6,17.5,6c10,0,16.9-5.7,16.9-16.8v-6.3c-3.8,5.3-9.5,10-18.1,10%20c-10.4,0-20.8-8-20.8-20.4v-0.2c0-12.5,10.4-20.5,20.8-20.5c8.6,0,14.5,4.5,18.1,9.7v-8.6h4.2v36.5c0,6.3-2,11.2-5.4,14.6%20c-3.8,3.8-9.4,5.7-15.7,5.7C418.1,82,411.4,79.7,405.4,75.3z%20M442.5,44.5v-0.2c0-10-8.9-16.5-17.8-16.5c-9.1,0-16.8,6.3-16.8,16.3%20v0.1c0,9.8,7.8,16.5,16.8,16.5C433.6,61,442.5,54.3,442.5,44.5z'/%3e%3cpath%20class='st1'%20d='M455.5,8h5.1v5.7h-5.1V8z%20M455.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M473.8,57V28.7h-6.3v-3.8h6.3V11h4.2v13.9h15.2v3.8H478v27.9c0,6.2,3.6,8.5,8.6,8.5c2.1,0,3.9-0.5,6.3-1.5%20v3.9c-2.3,1.1-4.4,1.5-7.1,1.5C479.2,69,473.8,65.4,473.8,57z'/%3e%3cpath%20class='st1'%20d='M496.7,55.5v-0.2c0-9.1,7.7-14,18.9-14c6,0,10.1,0.8,14.3,1.8v-1.8c0-8.8-5.3-13.3-14.2-13.3%20c-5.3,0-9.5,1.5-13.6,3.5l-1.5-3.6c4.7-2.3,9.4-3.8,15.4-3.8c5.9,0,10.6,1.7,13.6,4.7c2.9,2.9,4.4,6.8,4.4,12.2v27h-4.1v-7.2%20c-3,4.2-8.3,8.1-16.5,8.1C505.3,69.1,496.7,64.6,496.7,55.5z%20M530,51.9v-5c-3.6-0.9-8.5-2-14.6-2c-9.2,0-14.2,4.1-14.2,10.1v0.2%20c0,6.3,5.9,10,12.5,10C522.5,65.4,530,59.9,530,51.9z'/%3e%3cpath%20class='st1'%20d='M544.4,6.3h4.2v61.9h-4.2V6.3z'/%3e%3c/g%3e%3c/g%3e%3cpolygon%20points='20.5,8.6%2020.5,50.5%2048.1,50.5%2048.1,68.2%200,68.2%200,8.6%20'/%3e%3cpolygon%20points='76.7,8.6%2089,28.8%20101.3,8.6%20122.4,8.6%20122.4,68.2%20102,68.2%20102,40.4%2089.2,60%2088.4,60%2075.7,40.4%2075.7,68.2%2055.5,68.2%2055.5,8.6%20'/%3e%3cpath%20d='M163.5,33.1l-4.6,12.3h9.3L163.5,33.1z%20M153.6,8.2h20.1l25.1,60l-22.3,0l-3.1-7.9h-19.8l-3,7.9h-22L153.6,8.2z'/%3e%3cpolygon%20points='242.6,8.6%20235.1,19.8%20246.8,37.1%20266.1,8.6%20'/%3e%3cpolygon%20points='266.6,68.1%20246.7,38.7%20235.1,55.9%20243.4,68.1%20'/%3e%3cg%3e%3cpolygon%20class='st2'%20points='201.6,67.7%20221.9,37.8%20202.5,9.1%20224.7,9.1%20244.2,37.8%20223.9,67.7%20'/%3e%3cpath%20class='st3'%20d='M224.5,9.6l19.1,28.2l-19.9,29.4h-21l19.5-28.8l0.4-0.6l-0.4-0.6L203.4,9.6L224.5,9.6%20M225,8.6h-23.5%20l19.7,29.2l-20.6,30.4h23.5l20.6-30.4L225,8.6L225,8.6z'/%3e%3c/g%3e%3cg%3e%3clinearGradient%20id='SVGID_1_'%20gradientUnits='userSpaceOnUse'%20x1='220.9093'%20y1='-950.0897'%20x2='220.9093'%20y2='-925.641'%20gradientTransform='matrix(1%200%200%20-1%200%20-916)'%3e%3cstop%20offset='0'%20style='stop-color:%23FFFFFF'/%3e%3cstop%20offset='0.9448'%20style='stop-color:%23D83A16'/%3e%3c/linearGradient%3e%3cpath%20class='st4'%20d='M203.5,9.6h21l13.9,20.5c0,0-5.1,2.5-18.3,4L203.5,9.6z'/%3e%3c/g%3e%3clinearGradient%20id='SVGID_00000102544490061922048680000006716673136051575428_'%20gradientUnits='userSpaceOnUse'%20x1='-829.9603'%20y1='-469.8219'%20x2='-829.2181'%20y2='-469.8219'%20gradientTransform='matrix(0%2056.2842%20-56.2842%200%20-26433.2578%2046715.5)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000102544490061922048680000006716673136051575428_);'%20d='%20M1,43.5C6.8,41.1,13.7,39,19.6,38V9.6H1V43.5z'/%3e%3clinearGradient%20id='SVGID_00000103957968551173334310000005412737639992854954_'%20gradientUnits='userSpaceOnUse'%20x1='-824.1308'%20y1='-473.5818'%20x2='-823.3696'%20y2='-473.5818'%20gradientTransform='matrix(0%2040.0685%20-40.0685%200%20-18886.7422%2033025.9883)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000103957968551173334310000005412737639992854954_);'%20d='%20M89,30.6l-12.8-21H56.5v25.1c24.2-3,48.1-1.9,64.9,0.1V9.6H102L89,30.6z'/%3e%3clinearGradient%20id='SVGID_00000045609548158379760350000004638969150694955421_'%20gradientUnits='userSpaceOnUse'%20x1='-828.1707'%20y1='-470.2902'%20x2='-827.4019'%20y2='-470.2902'%20gradientTransform='matrix(0%2050.0393%20-50.0393%200%20-23369.248%2041443.8047)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000045609548158379760350000004638969150694955421_);'%20d='%20M154.3,9.2l-11.9,28.4c5.1,0.9,10.5,1.1,17.7,1.8l3.4-9.1l3.5,9.2c6.3,0.2,11.4-0.5,18.1-1.5L173,9.2L154.3,9.2L154.3,9.2L154.3,9.2%20z'/%3e%3clinearGradient%20id='SVGID_00000098218655395796564910000006749387513598408615_'%20gradientUnits='userSpaceOnUse'%20x1='-817.4011'%20y1='-476.8813'%20x2='-816.6498'%20y2='-476.8813'%20gradientTransform='matrix(0%2030.094%20-30.094%200%20-14101.042%2024605.1211)'%3e%3cstop%20offset='0'%20style='stop-color:%23000000'/%3e%3cstop%20offset='8.490400e-02'%20style='stop-color:%231E1E1D'/%3e%3cstop%20offset='0.2228'%20style='stop-color:%23444443'/%3e%3cstop%20offset='0.3965'%20style='stop-color:%236C6B6B'/%3e%3cstop%20offset='0.5991'%20style='stop-color:%239D9C9C'/%3e%3cstop%20offset='0.8233'%20style='stop-color:%23D4D4D3'/%3e%3cstop%20offset='1'%20style='stop-color:%23FFFFFF'/%3e%3c/linearGradient%3e%3cpath%20style='fill-rule:evenodd;clip-rule:evenodd;fill:url(%23SVGID_00000098218655395796564910000006749387513598408615_);'%20d='%20M243.1,9.6l-6.9,10.2l5.7,8.5c5.8-1.8,9.2-3.2,13.7-6l8.5-12.6H243.1L243.1,9.6z'/%3e%3c/svg%3e)
%20--%3e%3csvg%20version='1.1'%20id='Layer_1'%20xmlns='http://www.w3.org/2000/svg'%20xmlns:xlink='http://www.w3.org/1999/xlink'%20x='0px'%20y='0px'%20viewBox='0%200%20548.6%2081.8'%20style='enable-background:new%200%200%20548.6%2081.8;'%20xml:space='preserve'%3e%3cstyle%20type='text/css'%3e%20.st0{fill:%23B3B2B2;}%20.st1{fill:%23FFFFFF;}%20.st2{fill:%23EDEDED;}%20.st3{fill:%23B2B2B2;}%20.st4{fill:%23CB2A27;}%20.st5{fill:%239E2F2B;}%20.st6{fill:url(%23SVGID_1_);}%20%3c/style%3e%3cg%3e%3cg%3e%3cg%3e%3cpolygon%20class='st0'%20points='270.3,9.2%20268.5,9.2%20268.5,8.5%20272.9,8.5%20272.9,9.2%20271.1,9.2%20271.1,14%20270.3,14%20'/%3e%3cpolygon%20class='st0'%20points='273.5,8.5%20274.5,8.5%20276.3,13.1%20278.2,8.5%20279.1,8.5%20279.1,14%20278.5,14%20278.5,9.5%20278.5,9.5%20276.6,14%20276,14%20274.2,9.5%20274.2,9.5%20274.2,14%20273.5,14%20'/%3e%3c/g%3e%3c/g%3e%3cpath%20class='st0'%20d='M299.9,0h4.1v79.5h-4.1V0z'/%3e%3cg%3e%3cpath%20class='st1'%20d='M331.7,8.9h19.8c18.7,0,31.5,12.8,31.5,29.4v0.2c0,16.8-12.8,29.7-31.5,29.7h-19.8V8.9L331.7,8.9z%20M336.1,12.8V64h15.4c16.5,0,27-11.3,27-25.4v-0.2c0-14-10.4-25.7-27-25.7H336.1z'/%3e%3cpath%20class='st1'%20d='M390.3,8h5.1v5.7h-5.1V8z%20M390.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M405.4,75.3l2.4-3.3c5.1,3.9,11.2,6,17.5,6c10,0,16.9-5.7,16.9-16.8v-6.3c-3.8,5.3-9.5,10-18.1,10%20c-10.4,0-20.8-8-20.8-20.4v-0.2c0-12.5,10.4-20.5,20.8-20.5c8.6,0,14.5,4.5,18.1,9.7v-8.6h4.2v36.5c0,6.3-2,11.2-5.4,14.6%20c-3.8,3.8-9.4,5.7-15.7,5.7C418.1,82,411.4,79.7,405.4,75.3z%20M442.5,44.5v-0.2c0-10-8.9-16.5-17.8-16.5c-9.1,0-16.8,6.3-16.8,16.3%20v0.1c0,9.8,7.8,16.5,16.8,16.5C433.6,61,442.5,54.3,442.5,44.5z'/%3e%3cpath%20class='st1'%20d='M455.5,8h5.1v5.7h-5.1V8z%20M455.9,24.9h4.2v43.2h-4.2V24.9z'/%3e%3cpath%20class='st1'%20d='M473.8,57V28.7h-6.3v-3.8h6.3V11h4.2v13.9h15.2v3.8H478v27.9c0,6.2,3.6,8.5,8.6,8.5c2.1,0,3.9-0.5,6.3-1.5%20v3.9c-2.3,1.1-4.4,1.5-7.1,1.5C479.2,69,473.8,65.4,473.8,57z'/%3e%3cpath%20class='st1'%20d='M496.7,55.5v-0.2c0-9.1,7.7-14,18.9-14c6,0,10.1,0.8,14.3,1.8v-1.8c0-8.8-5.3-13.3-14.2-13.3%20c-5.3,0-9.5,1.5-13.6,3.5l-1.5-3.6c4.7-2.3,9.4-3.8,15.4-3.8c5.9,0,10.6,1.7,13.6,4.7c2.9,2.9,4.4,6.8,4.4,12.2v27h-4.1v-7.2%20c-3,4.2-8.3,8.1-16.5,8.1C505.3,69.1,496.7,64.6,496.7,55.5z%20M530,51.9v-5c-3.6-0.9-8.5-2-14.6-2c-9.2,0-14.2,4.1-14.2,10.1v0.2%20c0,6.3,5.9,10,12.5,10C522.5,65.4,530,59.9,530,51.9z'/%3e%3cpath%20class='st1'%20d='M544.4,6.3h4.2v61.9h-4.2V6.3z'/%3e%3c/g%3e%3cg%3e%3cg%3e%3cpolygon%20class='st2'%20points='0.5,67.9%200.5,9.1%2020.1,9.1%2020.1,51%2047.8,51%2047.8,67.9%20'/%3e%3cpath%20class='st3'%20d='M19.6,9.5v41.1v0.9h0.9h26.7v15.8H0.9V9.5H19.6%20M20.7,8.5H0v59.9h48.3V50.6H20.7V8.5L20.7,8.5z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='102.8,67.9%20102.8,38.8%2089.3,59.6%2088.9,59.6%2075.5,38.8%2075.5,67.9%2056.1,67.9%2056.1,9.1%2076.7,9.1%2089.3,29.6%20101.9,9.1%20122.4,9.1%20122.4,67.9%20'/%3e%3cpath%20class='st3'%20d='M121.9,9.5v58h-18.7v-27v-3.2l-1.8,2.7L89.2,59L76.8,39.8L75,37.1v3.2v27H56.6V9.5h19.8l12.1,19.8l0.8,1.4%20l0.8-1.4L102,9.5L121.9,9.5%20M122.9,8.5h-21.3L89.3,28.7L77,8.5H55.7v59.9h20.2V40.4l12.7,19.8h0.9l12.7-19.8v27.9h20.5V8.5H122.9%20z'/%3e%3c/g%3e%3cg%3e%3cpath%20class='st2'%20d='M177.5,67.9l-3.2-7.8h-20.5l-3,7.8h-21l24.8-59.3H174l24.8,59.3H177.5z%20M158.8,46h10.7l-5.3-14.2L158.8,46z'%20/%3e%3cpath%20class='st3'%20d='M173.7,9.1L198,67.5h-20.2l-2.9-7.2l-0.3-0.6H174h-19.9h-0.6l-0.3,0.6l-2.7,7.2h-20.1l24.4-58.4H173.7%20M158,46.5h1.4h9.4h1.4l-0.5-1.4L165,32.8l-0.9-2.4l-0.9,2.4l-4.7,12.4L158,46.5%20M174.3,8.1h-20.2l-25.2,60.2h22.2l3-7.8H174%20l3.2,7.8h22.3L174.3,8.1L174.3,8.1z%20M159.5,45.6l4.7-12.4l4.7,12.4H159.5L159.5,45.6z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='236.5,19.8%20243.7,9.1%20266.2,9.1%20247.7,36.2%20'/%3e%3cpath%20class='st3'%20d='M265.3,9.5l-17.7,26l-10.6-15.7L244,9.5L265.3,9.5%20M267.1,8.5h-23.5L236,19.6L247.8,37L267.1,8.5L267.1,8.5z%20'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st2'%20points='244.6,67.8%20236.7,56%20247.7,39.5%20266.8,67.8%20'/%3e%3cpath%20class='st3'%20d='M247.7,40.4l18.3,26.9h-21L237.3,56L247.7,40.4%20M247.7,38.8L236,56l8.3,12.4h23.2L247.7,38.8L247.7,38.8z'/%3e%3c/g%3e%3cg%3e%3cpolygon%20class='st4'%20points='202.4,67.9%20222.8,37.9%20203.3,9.1%20225.6,9.1%20245.1,37.9%20224.7,67.9%20'/%3e%3cpath%20class='st5'%20d='M225.3,9.5l19.2,28.2l-20.1,29.6h-21.1l19.6-29l0.5-0.6l-0.5-0.6L204.2,9.4h21.1%20M225.9,8.5h-23.5l19.9,29.3%20l-20.7,30.5H225l20.7-30.5L225.9,8.5L225.9,8.5z'/%3e%3c/g%3e%3cg%3e%3clinearGradient%20id='SVGID_1_'%20gradientUnits='userSpaceOnUse'%20x1='166.4754'%20y1='-918.2897'%20x2='166.4754'%20y2='-934.5494'%20gradientTransform='matrix(1.5092%200%200%201.5092%20-29.5361%201419.9884)'%3e%3cstop%20offset='0'%20style='stop-color:%23FFFFFF'/%3e%3cstop%20offset='0.9448'%20style='stop-color:%23D83A16'/%3e%3c/linearGradient%3e%3cpath%20class='st6'%20d='M204.2,9.5h21.1L239.2,30c0,0-5.1,2.4-18.4,3.9L204.2,9.5z'/%3e%3c/g%3e%3cpath%20class='st1'%20d='M0.9,43.6c5.9-2.4,12.7-4.5,18.7-5.6V9.5H0.9V43.6z'/%3e%3cpath%20class='st1'%20d='M89.3,30.6L76.5,9.5H56.7v25.2c24.3-3,48.3-2,65.2,0.2V9.5h-19.6L89.3,30.6z'/%3e%3cpath%20class='st1'%20d='M154.8,9.1l-11.9,28.5c5.1,0.9,10.6,1.1,17.8,1.8l3.5-9.2l3.5,9.2c6.3,0.2,11.5-0.5,18.3-1.5L173.7,9.1H154.8%20z'/%3e%3cpath%20class='st1'%20d='M244,9.5l-6.9,10.3l5.7,8.5c5.9-1.8,9.2-3.2,13.7-6l8.6-12.7H244z'/%3e%3c/g%3e%3c/g%3e%3c/svg%3e)


Tokenization Briefing: DTCC Brings Tokenization to the U.S. Markets
Quick Take
DTCC Brings Tokenization Into the Core of U.S. Markets
DTCC’s tokenization service is set to launch this month on three eligible networks, including Stellar, Canton and DTCC's own Collateral AppChain, which is expected to launch later this year. An SEC no-action letter issued on December 11, 2025, allows DTC to run the service for three years on a defined set of liquid assets including Russell 1000 stocks, ETFs tracking major indices, and Treasuries.
Firms can tokenize securities they hold at DTC and transfer them directly between registered wallets 24/7. The main benefit in this initial launch is that these tokenized securities can transfer outside DTC’s operating hours.
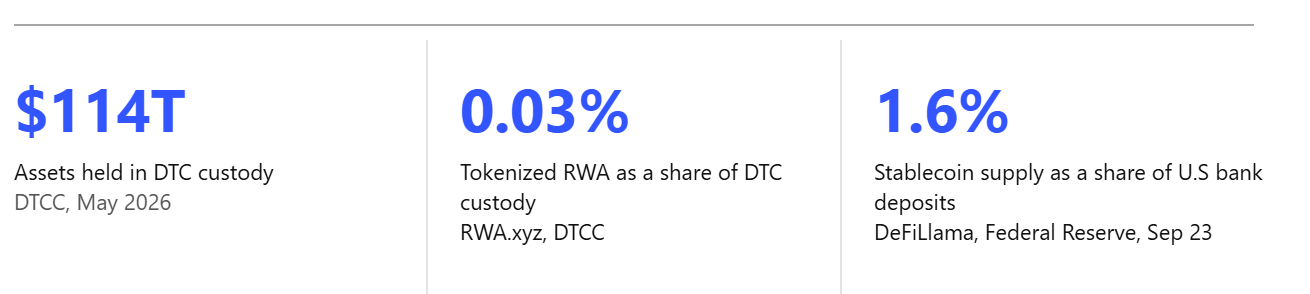
The tokenized RWA market comprises $38.8B of assets, which is about 0.03% of the $114T of assets held in DTC custody. Only part of that market falls in the asset classes DTCC’s service covers. Treasuries and stocks make up $18.1 billion, or 47%. The other $20.7 billion is spread across private credit, commodities, funds and other categories.
These assets wouldn’t move onto DTCC’s service, but they give a sense of scale. If DTC participants tokenized just 0.5% of the $114 trillion in custody, it would add about $570 billion, growing tokenized assets by roughly 1,470%. This scale is unlikely to materialize in the near term, but it shows how much room tokenized assets still have to grow.
The launch follows live trades on July 15, when about 40 firms converted DTC-held securities into tokens and used them in live transactions.
Tokenized Fixed Income Continues Expanding Beyond Treasuries
Two managers launched tokenized bond products over the last week. Plume launched nBND, a vault backed mainly by Fidelity’s Total Bond ETF. Baillie Gifford opened its tokenized bond fund, BAGEY, to professional investors in the UK, Switzerland, Hong Kong and the Cayman Islands.
Outside of Treasuries, tokenized fixed income has grown from $0.6 billion at the start of 2025 to $9.0 billion, according to RWA.xyz. That’s now about 60% the size of the $14.9 billion tokenized Treasury market. Private credit makes up $6.3 billion of the total, but corporate bonds are growing fastest, and that’s where these new products fit.
Wells Fargo Readies Tokenized Deposits
Stablecoin supply has more than doubled since January 2023, rising from $137 billion to $308 billion, while U.S. commercial bank deposits grew 10% to $19.6 trillion over the same period. Stablecoin growth has stalled so far in 2026, with supply flat at around $308 billion since January. Despite the flat growth this year, banks are responding to the rapid growth in 2024 and 2025.
Wells Fargo plans to launch tokenized deposits this fall for select corporate and commercial clients, starting with USD-to-GBP payments and expanding to all eligible clients and more currencies through 2027. Payments will route through tokenized deposits automatically when they improve speed or timing, so clients don’t need an onchain interface. Wells Fargo says its system can also connect to The Clearing House’s planned shared network.
Tokenized deposits let banks offer 24/7 settlement while keeping deposits on their balance sheets. Tokenized deposits are covered by FDIC insurance, and because the GENIUS Act doesn’t treat them as payment stablecoins, banks can pay interest on them. What’s still missing is interbank settlement. Each bank’s system is siloed, and The Clearing House’s shared network that would connect them isn’t expected until the first half of 2027.
Subscribe to Tokenization Briefing
Tokenization Briefing
Get 2 days early access to each issue by joining the mailing list.
© 2026 The Block Crypto, Inc. All Rights Reserved. Newsletters are provided for informational purposes only. It is not offered or intended to be used as legal, tax, investment, financial, or other advice.
More from Tokenization Briefing